

 Equity management
 Equity management
- Fund management
 Fund management
- Fund managementFund management
- Fund managementFund management


A stock grant is an award of company shares given to an employee, advisor, or other service provider as part of their compensation package. The defining feature is that the recipient does not buy the shares. The company gives them, typically with clauses in the form of a vesting schedule that requires the person to stay with the company or hit specific milestones before the shares become fully theirs. This schedule allows employees to earn ownership over time, encouraging them to stay with your company and contribute to its long-term success.
This structure is different from a stock option grant, where the company gives you the right to purchase shares at a fixed price rather than the shares themselves. That distinction drives almost everything else that separates the two, from taxation to risk profile.
The value of the stock grant can also fluctuate based on the company stock price in the stock market, offering additional financial upside if the company's performance improves. This makes stock grants an attractive form of compensation for companies seeking to conserve cash while still rewarding employees. For private companies, this can be especially valuable as it provides equity without requiring a cash outlay upfront.
In the United States, income tax obligations can arise based on the value of the stock grant at the time of vesting, which is considered ordinary income. Employees must consider the market price of the stock when planning for these taxes. For startups, ensuring compliance with the Internal Revenue Code and Securities and Exchange Commission (SEC) regulations is critical when offering stock grants.
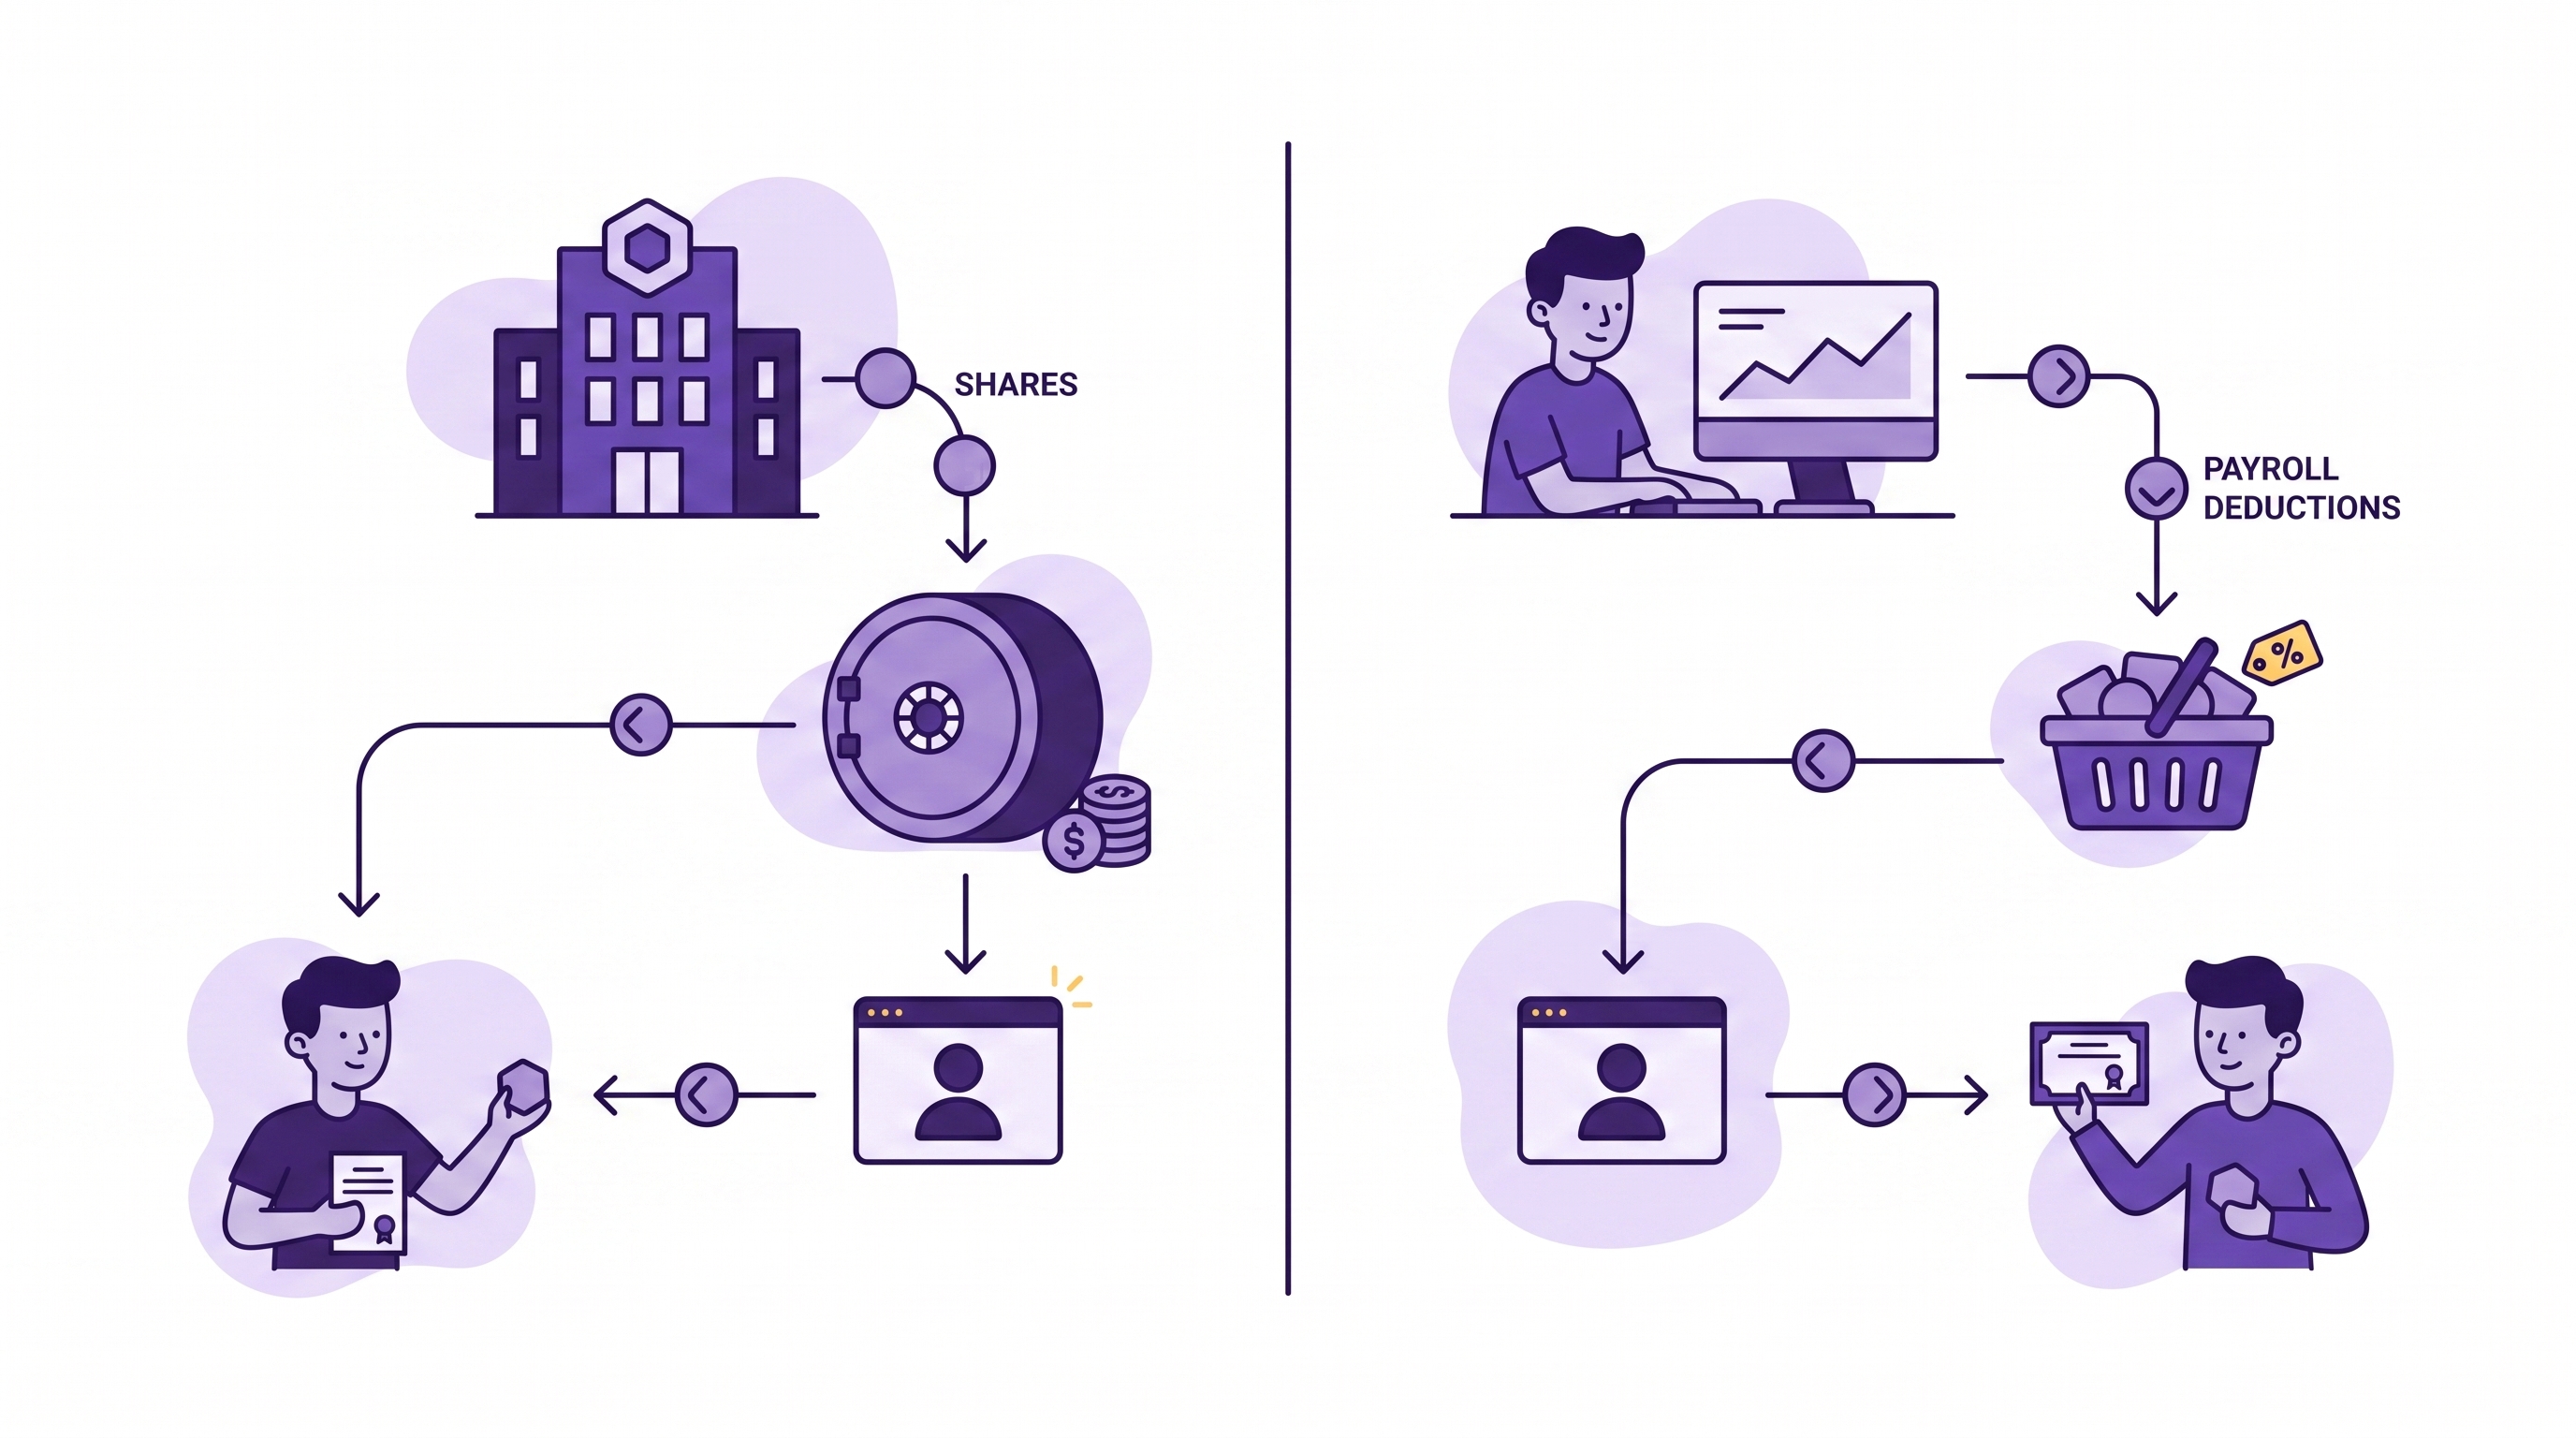
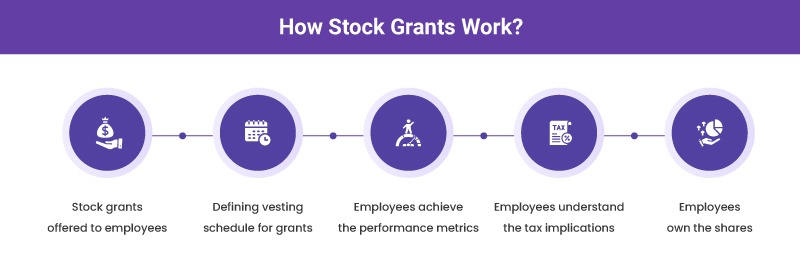
A stock grant gives employees a direct ownership stake in the company, almost always tied to a vesting schedule. Rather than handing over full ownership on day one, the shares are earned gradually as the employee stays with the business or hits agreed milestones. This keeps their financial interests tied to the company's long-term success. Here is how the process typically unfolds:
Restricted stock, one of the most common forms of stock grant, works differently from stock options. With restricted stock, employees receive the shares upfront at no cost, and the restrictions simply lift as vesting conditions are met. A stock option grant, on the other hand, only gives employees the right to buy shares later at a predetermined price, known as the grant price or exercise price, once the vesting period has passed.
Vesting schedules are a core component of stock grants. They define when employees earn full ownership of their shares, whether over a period of time or upon meeting specific conditions. Below are the four vesting structures companies commonly use:
Not all stock grants are built the same way. The two dominant structures are restricted stock units and restricted stock awards, with performance-based variants layered on top of each.
Restricted stock units (RSUs). An RSU is a promise from the company to deliver shares once vesting conditions are met. You do not own the underlying shares until they vest and settle. RSUs are the most common form of stock grant at public companies and later-stage private companies. Private company RSUs often carry double-trigger vesting, which means shares only settle when both a time condition and a liquidity event, such as an IPO or acquisition, have occurred.
Restricted stock awards (RSAs). An RSA delivers actual shares on the grant date, but the shares remain subject to forfeiture or repurchase until they vest. RSAs are favored by very early-stage companies when the fair market value of the stock is minimal, because recipients can take ownership at little to no cost and make an 83(b) election to lock in favorable tax treatment early.
Performance shares (PSUs and PSAs). These are RSUs or RSAs with vesting tied to performance goals rather than time alone. The number of shares that ultimately vest can scale up or down depending on how the company performs against targets such as earnings, stock price, or strategic milestones.
Stock grants solve several problems at once for employers, which explains why they have become a standard part of compensation planning.
They attract talent without draining cash- Startups and growth-stage companies often cannot match the salaries offered by established players. Equity closes that gap by offering meaningful upside in exchange for a lower cash outlay today.
They improve retention- Because unvested shares are forfeited on departure, a vesting schedule gives employees a concrete financial reason to stay. Each vesting date represents real value earned, and walking away means leaving the remainder on the table.
They align incentives- When employees hold shares, they benefit directly from decisions that grow the company's value. That shared upside encourages an ownership mindset across the team rather than a purely transactional relationship with the business.
They deliver value more reliably than options- A share of stock has value as long as the company has value. This makes grants attractive to employees who want compensation they can count on, and attractive to companies that want their equity awards to actually feel like compensation even in flat or down markets.
This comparison confuses more people than any other topic in equity compensation, so it is worth walking through carefully.
A stock option grant gives you the right to purchase a set number of shares at a fixed exercise price (also called the strike price) within a defined window, usually after vesting. You do not own anything until you exercise, which means paying the exercise price out of pocket. A stock grant, by contrast, delivers shares to you as they vest with no purchase required.
Tax treatment is where stock grants demand the most attention, because the timing and character of the tax differ from what many people expect.
When employees receive stock grants, they are taxed as ordinary income at the time of vesting. This means the value of the stock at vesting is considered taxable income, and employees must pay taxes on this amount. It is essential to plan for this tax obligation to avoid unexpected financial burdens.
If employees later decide to sell their vested shares, they may be subject to capital gains tax. The difference between the sale price and the value at the time of vesting determines the capital gain. If the shares are held for more than a year before being sold, they qualify for long-term capital gains tax, which is generally lower than short-term capital gains tax.
To manage the tax impact of stock grants, it's important to engage in effective tax planning. You might encourage employees to:
Set aside funds for taxes: Since stock grants are taxed as income when they vest, employees should plan to cover their tax liabilities. Consider advising them to set aside a portion of their salary or bonuses to meet these obligations.
Consider holding shares for long-term gains: If employees expect the stock price to rise, holding onto the shares for over a year can reduce their tax burden through long-term capital gains rates.
Consider 83(b) Election: For some types of stock grants, filing an 83(b) election allows for payment of taxes on the grant date rather than the vesting date. This helps potentially reduce overall tax liability if the stock appreciates significantly.
Consult a tax advisor: Navigating the tax implications of stock grants can be complex. You might recommend that employees consult a tax professional to create a strategy that best fits their financial situation.
Stock grants are a powerful compensation tool, but they come with practical challenges for both employees and companies. Here are the key issues to plan for:
A stock grant is one of the most direct ways a company can turn employees into owners. Shares are awarded, they vest over time, and once vested they belong to the recipient with no purchase required. That simplicity is exactly what separates grants from stock options, which demand an exercise price and carry the risk of expiring worthless.
For employees, the priorities are clear: read your grant agreement closely, understand your vesting schedule, plan for the tax hit at vesting, and avoid letting a single stock dominate your financial life. For companies, stock grants remain one of the most effective tools for hiring, retention, and alignment, provided the equity plan is administered accurately and the dilution math is well understood.
Equity compensation rewards the people who take the time to understand it. Whether you are receiving a stock grant or designing a grant program, the details in the paperwork matter far more than the headline number of shares.
Yes, stock grants are considered taxable income when they vest. At the time of vesting, the fair market value of the stock is treated as ordinary income for tax purposes. This amount is added to the employee's taxable income, and taxes are due even if the shares are not sold immediately. Employees may also be subject to capital gains tax if they sell the shares later.
The main difference between a stock option and a stock grant is that stock options give employees the right to purchase shares at a predetermined price, while stock grants provide shares outright, typically with a vesting schedule.
Stock grants are awarded to employees without requiring them to purchase the shares. However, they are not entirely 'free' as they are considered taxable income once they vest. The employee is responsible for paying taxes on the FMV of the shares when they vest, even if the shares are not sold immediately.
If you choose not to accept a stock grant, you forfeit the right to the shares. In most cases, stock grants are part of a compensation package and declining them means missing out on potential ownership in the company. You would not be liable for any taxes, as you would not receive any shares or associated financial benefits.
Generally not at the moment of grant. For RSUs and most restricted stock awards, the taxable event happens at vesting, when the FMV of the shares vested is taxed as ordinary income through payroll. The exception is a restricted stock award paired with an 83(b) election, which moves the tax event to the grant date, or an unrestricted stock grant, which is taxable immediately because there are no vesting conditions.