

 Equity management
 Equity management
- Fund management
 Fund management
- Fund managementFund management
- Fund managementFund management
An option pool is a block of company equity reserved for future grants to employees and other eligible contributors. It gives a startup room to offer equity as it hires, but it also affects the ownership percentages shown on a fully diluted cap table.
The right pool is not simply the largest pool a company can create. It should be large enough to support the hiring plan until the next funding milestone without creating unnecessary founder dilution.
This guide explains option pools from initial planning and approvals to dilution and long-term administration.
An option pool is a fixed number of shares reserved under a company’s employee equity plan for future grants. It is usually shown as a percentage of the company’s fully diluted equity, which assumes that all reserved shares, outstanding options, and other convertible securities have become shares.
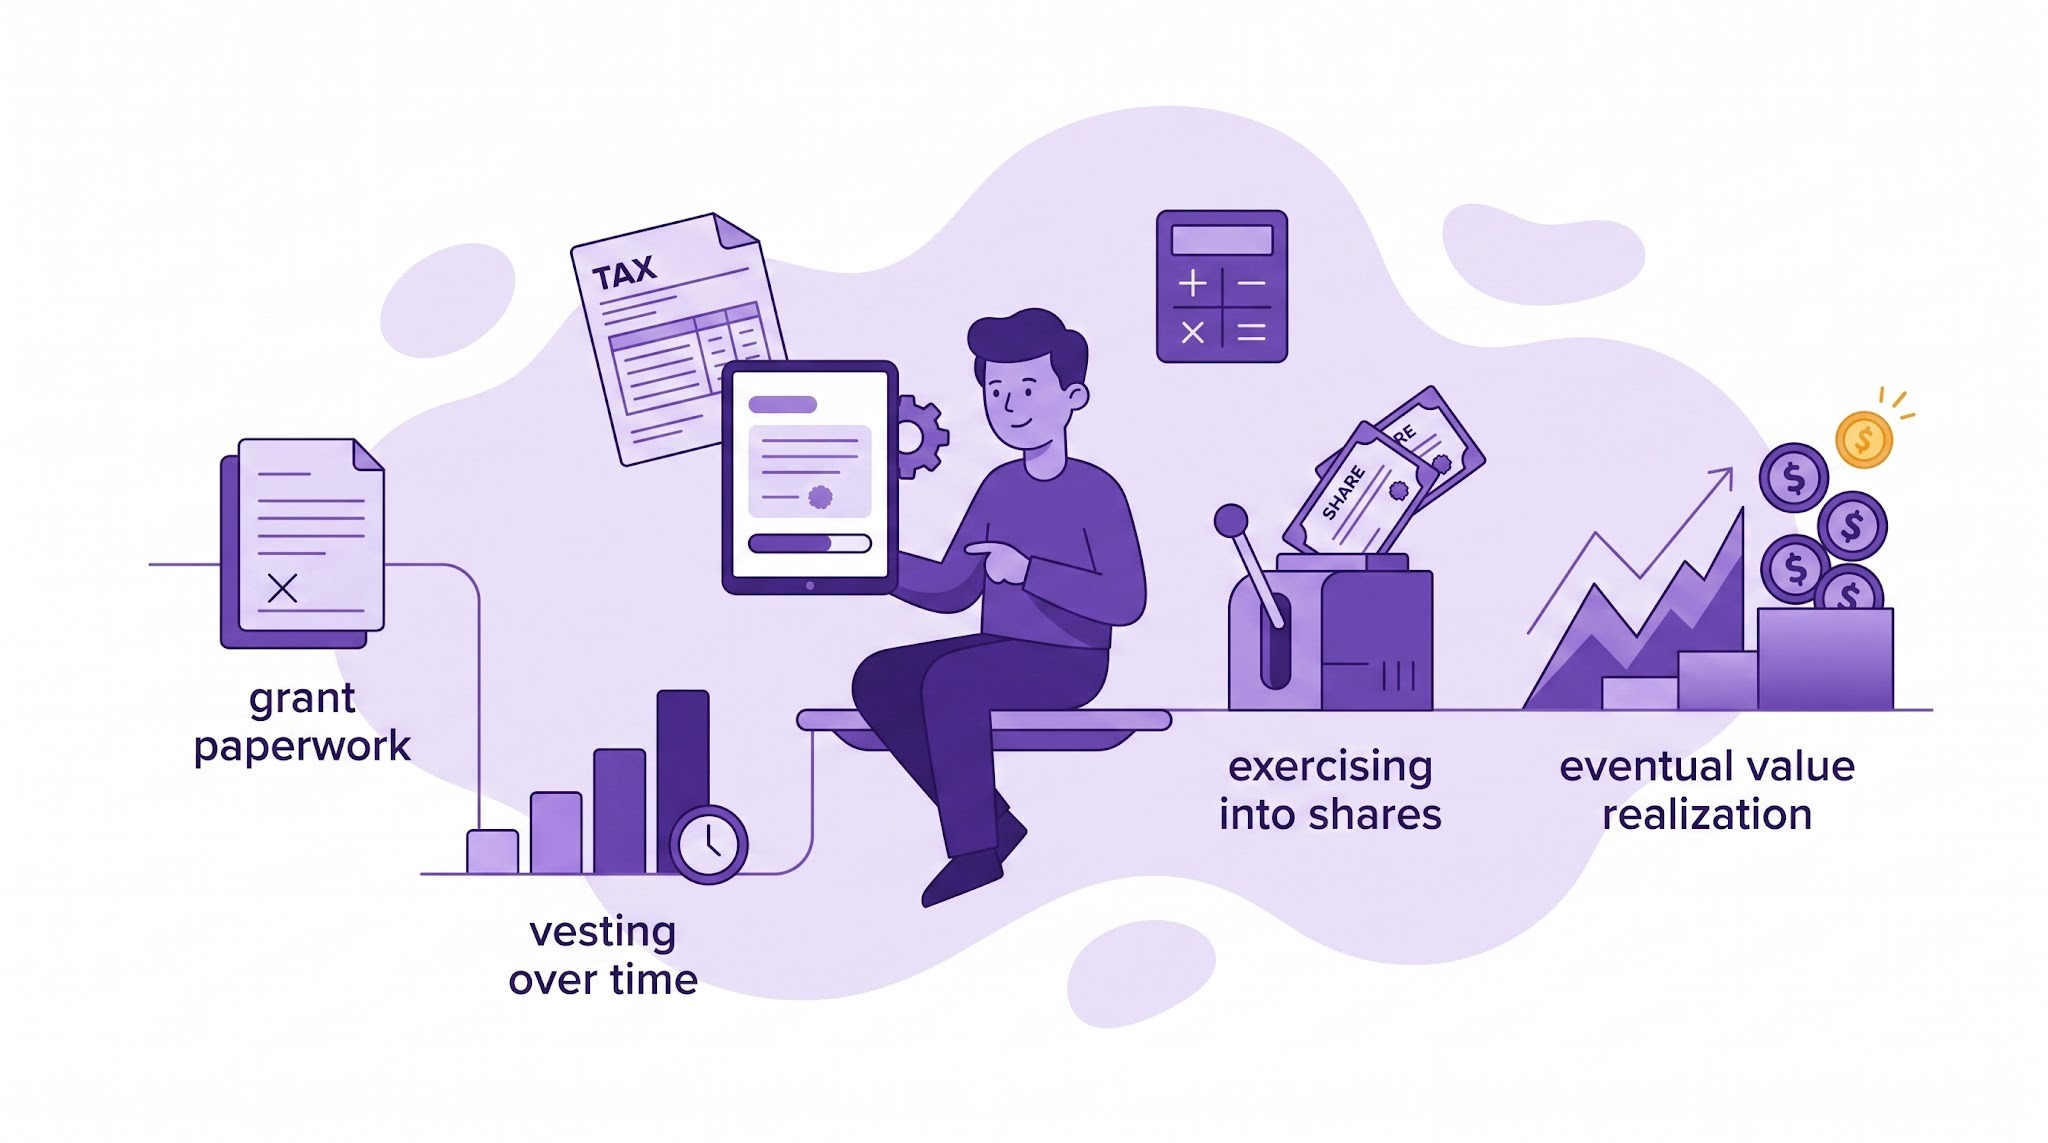
The pool itself does not give employees immediate ownership. An employee first receives an option grant. The option normally vests over time, and the employee becomes a shareholder only after exercising vested options and receiving shares.
For example, suppose a company has 10,000,000 shares after accounting for a newly created 10% option pool. In that case, 1,000,000 shares are reserved for future grants, while the remaining 9,000,000 shares represent the other shareholders on a fully diluted basis.
An option pool moves through a simple cycle:
1. Reserve: The company creates a pool containing a specified number of shares.
2. Grant: The company approves an option grant for an eligible employee or other recipient.
3. Vest: The recipient earns the right to exercise the options according to the vesting schedule.
4. Exercise: The recipient pays the exercise price for vested options.
5. Issue: The company issues shares, and the recipient becomes a shareholder.
The company must track the pool at each stage. Reserved but ungranted shares, granted options, vested options, exercised options, and canceled options have different meanings. Combining them into one figure can lead to incorrect hiring plans and cap table records.
If an employee leaves before some options vest, the unvested options generally lapse under the plan and grant terms. Those options may return to the available pool. The treatment of vested but unexercised options depends on the plan documents and the employee’s grant agreement.
Startups create option pools to support recruitment, retention, and long-term employee incentives. Equity can form part of a compensation package when a young company needs to conserve cash or compete for experienced hires.
An option pool can also bring discipline to equity planning. It gives founders, the board, and investors a clear view of how much equity is available for expected hires. During a funding round, investors review the available pool to assess whether the company has enough equity for its hiring plan after the investment.
A pool should not be created only because a standard percentage appears common in the market. Its size should reflect the roles the company expects to fill, the grants those roles may require, and the period the pool needs to cover.
Creating an option pool requires a hiring forecast, an equity incentive plan, corporate approvals, and accurate cap table records. The company should calculate the reserve from expected grants instead of selecting a percentage based only on a market benchmark.
1. Forecast future equity grants: List the employees and other eligible service providers the company expects to engage before its next funding round or major business milestone. Include expected new-hire grants, retention awards, and refresh grants.
2. Determine the required pool size: Add the expected grants and convert the result into a percentage of fully diluted capitalization. Current market guidance identifies 10% - 15% as a common reference range, but the final pool should reflect the company’s actual hiring requirements.
3. Adopt an equity incentive plan: Prepare a written plan that defines the total share reserve, eligible participants, available award types, vesting rules, exercise terms, expiration provisions, and administrative authority.
4. Obtain the required approvals: The board generally approves the plan, option pool, and individual grants under the company’s governing documents and applicable corporate law. Stockholder approval may also be required. For incentive stock options, federal tax rules require stockholder approval of the plan within 12 months before or after its adoption.
5. Address valuation and securities requirements: Before granting stock options, a private company commonly obtains a 409A valuation to support the fair market value of its common stock and set the exercise price. Private companies may rely on SEC Rule 701 for qualifying compensatory awards, subject to its eligibility, volume, and disclosure conditions. State securities laws may also apply.
6. Record and monitor the pool: Add the approved reserve to the fully diluted cap table and track grants, vesting, exercises, cancellations, expirations, and available capacity. Review the balance before major hiring cycles and financing rounds.
Creating or expanding the pool reduces existing shareholders’ ownership on a fully diluted basis. Once the full reserve is included in the fully diluted cap table, issuing a grant from that reserve generally moves equity from the unallocated pool to a recipient without increasing the fully diluted total.
The most useful method starts with planned hires and then checks the result against appropriate market data.
Bottoms-up sizing calculates the option pool from the company’s expected grants. List each planned role, estimate its grant using current compensation data, add the grants, and include a documented reserve for retention or unexpected hiring. Convert the total into a percentage of fully diluted capitalization.
Top-down sizing compares the calculated requirement with relevant market benchmarks and investor expectations. It is a useful check, but it should not replace the hiring plan.
If a benchmark suggests 10% while the documented hiring plan requires 7.5%, founders can explain the difference. If the hiring plan requires a pool above the benchmark, the company can show which roles account for the additional equity.
There is no single percentage that suits every startup. A practical pool should cover planned grants until the next funding or hiring milestone, plus a reasonable buffer.
The final percentage depends on:
A pool that is too small may require an early top-up. A pool that is too large can reduce existing shareholders fully diluted ownership before the extra capacity is needed.
The timing of a new pool or pool increase determines who bears the dilution.
A pre-money option pool is created or expanded before a new investment closes. The additional pool shares are included in the company’s pre-money capitalization, so the dilution falls on founders and other existing shareholders. The incoming investor purchases its ownership percentage after the pool increase has been included. All other terms being equal, a larger pre-money pool results in a lower investment price per share and a smaller ownership percentage for existing holders.
A post-money option pool is created or expanded after the new investment. As a result, the dilution is shared by existing shareholders and the incoming investor. This treatment is generally more favorable to founders because the investor also absorbs part of the pool dilution. The company should still size the pool from its hiring requirements, since excess capacity reduces every shareholder’s ownership.
A term sheet may request a pool equal to a specified percentage of the post-financing company while requiring the pool increase to occur pre-money. Founders should therefore confirm both the target pool percentage and which shareholders will bear the dilution.
Creating or expanding an option pool reduces the percentage ownership of existing shareholders on a fully diluted basis.
Granting options from a pool that is already included in the fully diluted cap table usually uses part of the existing reserve. It does not increase the fully diluted share count by itself.
If a company has 10,000,000 existing shares and wants the new pool to equal 10% of the total after creation, it cannot simply reserve 1,000,000 shares.
The calculation is
Pool shares = Existing shares × Target pool percentage ÷ (1 − Target pool percentage)
Pool shares = 10,000,000 × 10% ÷ 90% = 1,111,111 shares
After the pool is created:
Founders should also model the pool together with any new investment.
Consider a simplified round in which an investor is expected to own 20% and the desired pool is 10% after the transaction:
An option pool should be reviewed regularly, especially before a hiring cycle or funding round.
A simple review should cover:
The company should reconcile these figures with its cap table and supporting records. It should also model pool increases before agreeing to a term sheet.
This gives founders a clearer view of the ownership effect and gives the board a sound basis for approving future grants.
Treat the option pool as a controlled equity budget with one accountable owner. A short pool memo for each proposed change should record the business reason, requested share count, capitalization basis, approval path, and effect on current holders. That document gives decision-makers a consistent record for later audits and due diligence.
An effective option pool begins with expected hires, not a standard percentage. Founders should estimate future grants, model the dilution, agree on a realistic buffer, and maintain accurate records as options move through grant, vesting, exercise, expiration, or cancellation.
Qapita supports option pool and grant tracking alongside cap table administration. Contact Qapita to discuss how your company can manage its employee equity records and future pool requirements.
The option pool shuffle occurs when an investor asks a company to create or enlarge an option pool before the investment closes. Because the increase is included in the pre-money capitalization, existing shareholders absorb the dilution, while the incoming investor buys its agreed post-round percentage. Founders can evaluate the request by comparing the proposed pool with the company’s actual hiring plan and modeling the post-round cap table.
An option pool does not automatically change the headline pre-money valuation in a term sheet. A pre-money pool increase adds shares to the capitalization used to calculate the investment price per share. This can reduce the effective economic value attributed to the existing shareholders even when the headline valuation stays the same.
Yes. A company can increase its option pool when it needs capacity for future grants, subject to the approvals required by law, its governing documents, and investment agreements. A reduction may also be possible, but the company must consider existing grants, contractual commitments, and the applicable approval process.
Shares that were reserved but never granted remain available under the pool until the plan is amended, expires, or is otherwise changed. Options that expire or are canceled may return to the pool if the plan documents permit it. Unallocated pool shares should not be described as employee options that have expired or been repurchased because no individual grant was made.
If the full pool is already included in the fully diluted cap table, a grant from that pool usually moves options from the unallocated reserve to a recipient without increasing the fully diluted total. Creating or expanding the pool is the event that generally creates additional fully diluted dilution. The legal share count changes when options are exercised and shares are issued, but the fully diluted cap table anticipates that outcome.