

 Equity management
 Equity management
- Fund management
 Fund management
- Fund managementFund management
- Fund managementFund management
Form 3922 is widely known as the 'Transfer of Stock Acquired Through an Employee Stock Purchase Plan Under Section 423(c)'. It is an important tax document to intimate the Internal Revenue Service (IRS) regarding the transfer of stock obtained through an ESPP.
This form captures key details about the stock purchase, such as the exercise price, the stock's fair market value (FMV) on the purchase date, and the date on which the employee acquired the shares.
Form 3922 is primarily used for informational purposes only. It is not directly reported on the employee's tax return unless they sell the acquired stock. However, the information provided on Form 3922 is essential for employees to accurately report their stock-related tax liabilities when they sell the shares.
For example, let's consider an employee, Maria, who purchased 100 shares of your startup's stock at a discounted price of $20 per share through an ESPP. The FMV on the purchase date was $25 per share. As Maria acquired the shares at a price lower than FMV, this transaction triggered the need for Form 3922.
If Maria sells the shares at a price higher than her adjusted cost basis, she will have a capital gain. Alternatively, if she sells below her adjusted cost basis, she will have a capital loss. (Her cost basis isn't just the $20 she paid, see "How to Calculate Your Cost Basis Using Form 3922" below for how the bargain element factors in.) Form 3922 features the necessary information to calculate these gains or losses, therefore helping Maria accurately report her stock-related tax liabilities.
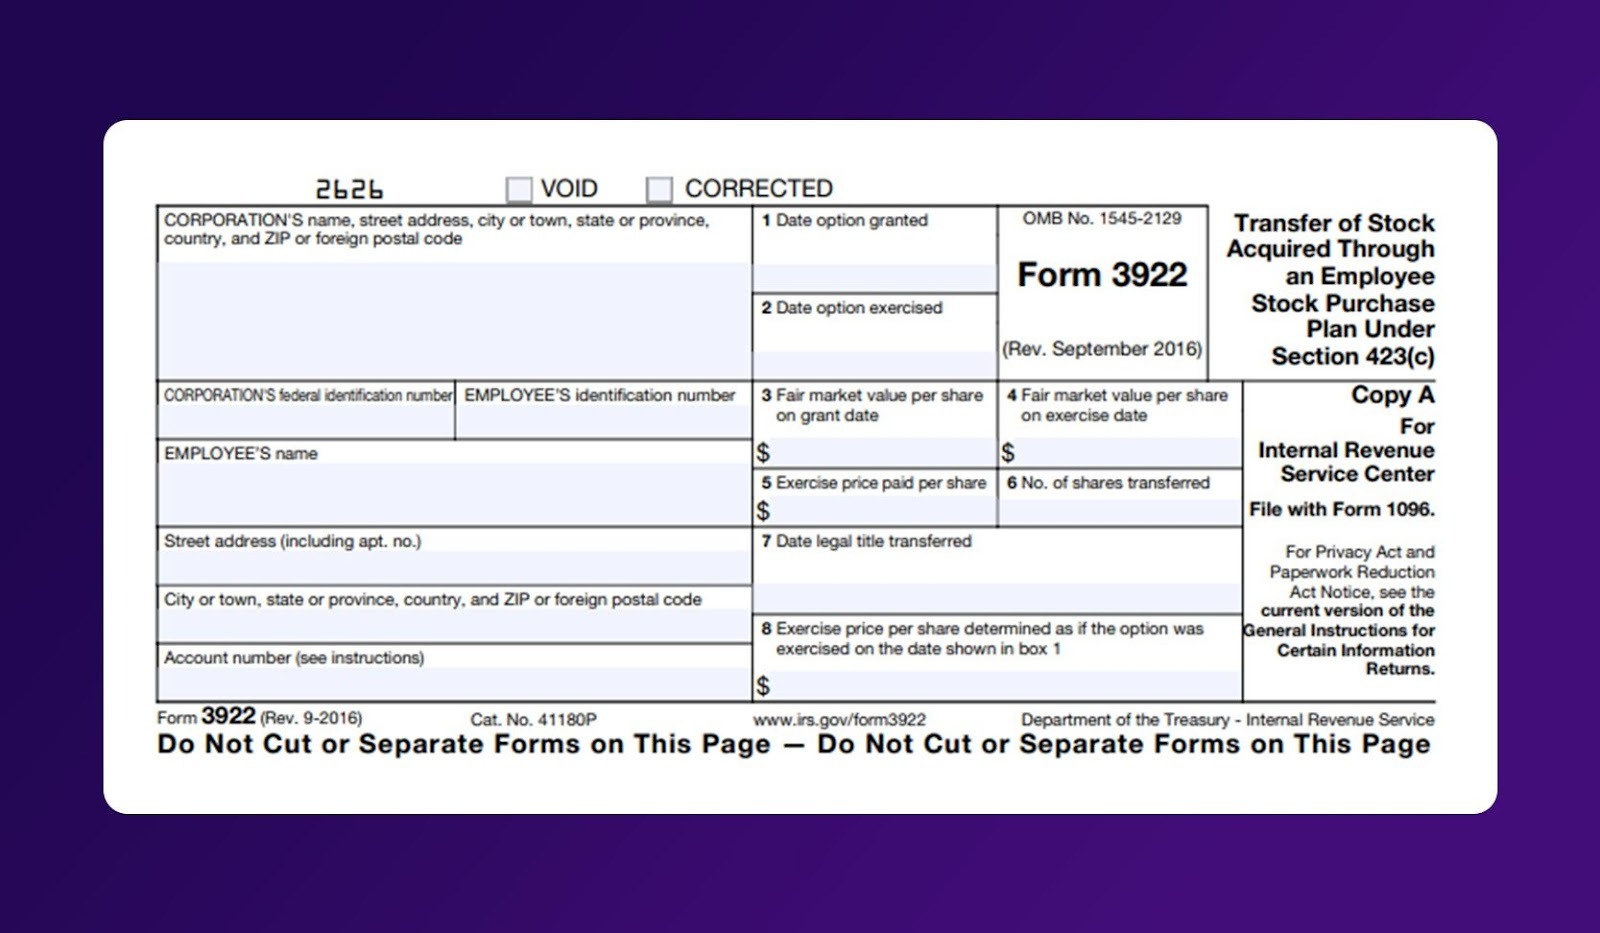
If you participated in your ESPP across more than one purchase period in the same year, you will receive a separate Form 3922 for each transfer, not one consolidated form. Each form reports the exercise price, fair market value, and transfer date for that specific purchase period only, so keep every copy. When you eventually sell shares from multiple purchase periods, you will need the matching Form 3922 for each lot to calculate cost basis correctly.
ESPPs provide employees an opportunity to invest in the company's stock and potentially benefit from any future appreciation in value. ESPPs have been created to foster employee ownership and align their interests with the enterprise's performance. Employees can acquire these plans at a discounted price directly from their payroll, making the entire process a seamless experience.
Participating in an ESPP can have significant tax implications for employees. One key aspect is the 'bargain element,' which represents the difference between the FMV of the stock on the purchase date and the actual purchase price. Form 3922 plays a crucial role in this process. It provides the necessary information to calculate the bargain element and any capital gains or losses from the sale of the shares.
The bargain element is considered ordinary income and is subject to income tax withholding. Additionally, when employees sell the acquired stock, they might need to pay capital gains taxes on any appreciation in value since the purchase date. The holding period of the stock, whether short-term (held for one year or less) or long-term (held for more than one year), can impact the tax treatment of any gains realized from the sale.
The IRS taxes short-term capital gains at higher rates than long-term gains, so understanding the holding period of the stock acquired through an ESPP is essential for employees to plan their tax strategies effectively.
When it comes to tax forms related to stock transactions, it is important to distinguish between Form 3922 and Form 3921. These forms are often confused due to their similar names and purposes, but they serve distinct functions and have unique reporting requirements.
Form 3921 is specifically designed to report transactions related to Incentive Stock Options (ISOs). ISOs are stock options granted to employees with the aim of providing them with a stake in the company. When an employee exercises ISOs, the company is required to report this transaction on Form 3921. This form helps the IRS determine the appropriate taxes due to the employees' exercise of ISOs.
On the other hand, Form 3922 is meant to inform the IRS about the first transfer of legal title of stock acquired through ESPP. Form 3922 provides details like the date of transfer, FMV of the stock, and the exercise price per share.
The key distinction between Form 3921 and Form 3922 lies in the type of stock transactions they report. Form 3921 focuses on ISOs, while Form 3922 pertains to ESPPs.
Form 3922 serves as a crucial tool in the financial ecosystem of startups. Here's why:
1. Precise Record-keeping: Form 3922 captures key details about the ESPP transaction, including the stock purchase price, FMV on the grant and exercise dates, and the number of shares acquired. This information serves as the foundation for determining your employees' cost basis, a crucial factor in calculating capital gains taxes.
2. Taxable Income Clarity: The difference between the purchase price and the FMV on the exercise date can trigger a tax event for your employees. Form 3922 helps them understand if they owe ordinary income taxes on this difference.
3. Avoiding Tax Issues: Inaccurate reporting or the absence of Form 3922 can lead to significant tax headaches for your employees later on. The IRS may question the cost basis reported on their tax return, potentially resulting in penalties and adjustments.
When employees purchase company stock at a discounted price through an ESPP, as an employer, you must report this transaction by issuing Form 3922. You have to submit the form to the IRS and provide a copy of the form to the employee who made the purchase. This dual filing ensures that both the IRS and the employee have accurate records of the transaction.
Employees who receive company stock through an ESPP are also required to keep a copy of Form 3922 for their tax records. Employees need not include the information in this form on their tax returns if they do not sell any of the acquired company stocks. However, having this form is crucial for maintaining accurate records of stock transactions and potential tax implications.
No, not directly. Form 3922 is an informational document, so you do not enter figures from it on your tax return in the year you receive it. The IRS already has a copy, which is why the form exists: to give both you and the IRS matching records for later.
You only need the numbers on Form 3922 when you sell the shares it covers, at which point they determine your cost basis and how much of the sale is taxable. Keep every Form 3922 you receive until you have sold the corresponding shares. There is no separate deadline for using the form itself; it simply waits in your records until a sale triggers the need for it.
The dates on Form 3922, specifically the option grant date and the exercise (transfer) date, determine whether your eventual sale counts as a qualifying or disqualifying disposition, and that distinction changes your tax bill.
A sale is a qualifying disposition if it happens at least two years after the grant date and at least one year after the exercise date. In this case, only the discount portion (up to the plan's allowed limit) is taxed as ordinary income, and the rest of any gain is taxed at the more favorable long-term capital gains rate.
A sale that misses either holding period is a disqualifying disposition. Here, the entire bargain element, the difference between the fair market value on the purchase date and what you paid, is taxed as ordinary income in the year of sale, regardless of how long you held the shares afterward. Any additional gain beyond that is taxed as a capital gain, which may be short-term or long-term depending on your holding period from the purchase date.
Because Form 3922 has the grant date, exercise date, and FMV figures, it is the document you need on hand to determine which category applies before you file.
Form 3922 and Form 1099-B report two different events in the life of your ESPP shares, and confusing them is one of the most common cost basis mistakes employees make.
Form 3922 reports the purchase, the transfer of stock into your name under the ESPP. Your employer files it in the year you buy the shares, and it exists purely for recordkeeping. It never reports a sale and never appears on your tax return by itself.
Form 1099-B reports the sale. Your broker issues it in the year you sell the shares, and it does go directly on your tax return through Schedule D and Form 8949.
The connection between the two is cost basis. Form 1099-B is supposed to report your basis, but because brokers often omit the ordinary income portion of ESPP shares, the basis on Form 1099-B is frequently understated. Form 3922 is the document you use to correct it before you file.
An exemption can be obtained from the IRS when the original transfer of stock ownership is completed by either:
This exemption is limited to any tax year within the period starting from when the stock option was granted to them and ending when they first acquired ownership of the ESPP shares.
Form 3922 includes several data fields that provide essential information for accurate tax reporting. These fields include:
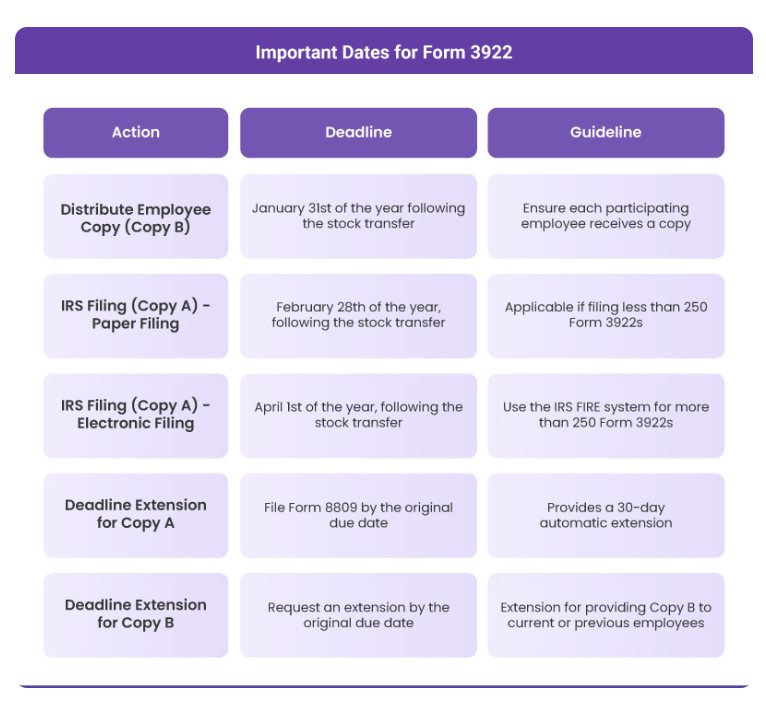
Meeting the deadlines for IRS Form 3922 is crucial to avoid potential penalties from the IRS. Here is a breakdown of the key dates to remember:
1. Employee Copy (Copy B): You must distribute a copy of Form 3922 (Copy B) to each participating employee by January 31st of the year following the calendar year in which the stock transfer took place. This ensures they have the information readily available for their tax filings.
2. IRS Filing (Copy A): There are two options for filing Copy A with the IRS:
3. Deadline Extension: You can request a 30-day automatic extension to file Copy A with the IRS by submitting Form 8809, no justification is required. You must file this form by the original due date for the extension to be valid.
If these dates fall on a Saturday, Sunday, or legal holiday, the due date moves to the next business day. Missing these deadlines can result in penalties from the IRS. Make sure to factor them into your ESPP administration process to ensure timely compliance.
Once you have submitted Form 3922s, you must store them safely for easy access during tax return filings. Here are some best practices to help you with the process:
1. Maintain Both Digital and Physical Copies: Having both digital and physical backups of Form 3922 and related ESPP documents ensures you can access the information easily when needed. Cloud storage platforms or secure servers are good options for storing digital copies. Keep physical copies at the designated document storage area in the office.
2. Organize All Relevant Documents: Keep all documents related to your ESPP program organized, including plan documents, stock purchase agreements, and any communications with employees. Categorize and label documents for quick retrieval when needed.
3. Review and Update Records Regularly: Review your ESPP records regularly to ensure their accuracy. This might involve necessary changes to the stock plan or employee participation.
4. Comply with IRS Guidelines: The IRS requires employment tax records, the closest category Form 3922 falls under, to be kept for at least 4 years after the date the tax becomes due or is paid, whichever is later. You must stay updated about any updates to IRS regulations that may impact your record-keeping practices.
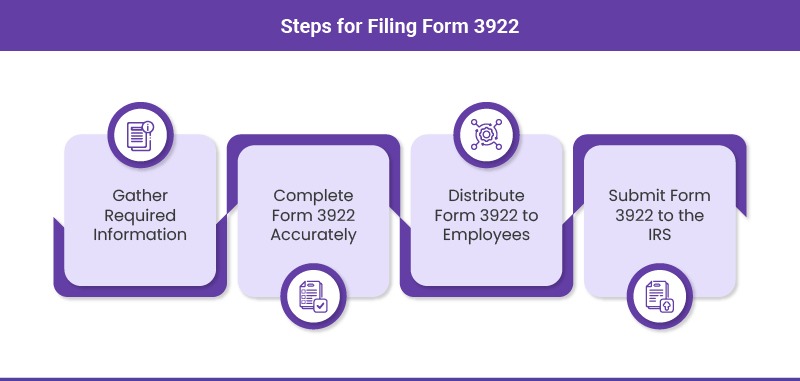
Here is a step-by-step guide to help you complete and submit Form 3922 efficiently:
Collect essential details related to the stock transfer. This includes the employee's name, Social Security Number (SSN), stock transfer date, FMV of the stock on the transfer date, and the exercise price per share.
Fill out Form 3922 with the gathered information. Ensure accuracy and double-check all entries to avoid errors. Any discrepancy can lead to potential tax issues with the IRS.
Provide Copy B of Form 3922 to the employee who acquired company stock through the ESPP. Employees need this form for their tax records.
File Copy A of Form 3922 with the IRS by the last business day of February if filing on paper (Form 1096 must accompany paper submissions), or by March 31 if filing electronically, of the year following the calendar year of the stock transfer. Remember that electronic filing is mandatory if your total information returns of all types reach 10 or more for the year. You can submit Form 3922 electronically through the IRS's filing information returns electronically (FIRE) system or the newer IRIS portal.
Failing to file Form 3922 or inaccurately submitting it can lead to significant penalties for employers. The IRS imposes fines based on the delay and the accuracy of the information provided. The penalty amount differs for small businesses, defined as those with average gross receipts of $5 million or less over the last three years.
1. $60 per form if the filings are 30 days late, up to a maximum of $630,500 per year. The maximum penalty is $220,500 for small businesses.
2. $120 per form if the filings are made by August 1st, up to a maximum of $1,891,500 per year. The maximum penalty for small businesses in this case is $630,500.
3. $310 per form for failure to file up to an annual maximum of $3,783,000. The penalty for small businesses here is $1,261,000.
If it is established that you have deliberately failed to submit the return or have furnished incorrect information, then the penalty is $630 per statement. There is no capping on the maximum penalty in this case.
This penalty applies separately to the copies to be submitted to the IRS and to be provided to the employee or ex-employee. If you are unable to provide copies of both, the penalties mentioned above and the maximum capping are both doubled.
Form 3922 is a key part of managing an Employee Stock Purchase Plan the right way. It records essential details about the stock transfer, including the exercise price, fair market value on the purchase date, and when the employee acquired the shares.
While it's mainly for informational purposes, this information becomes critical when employees eventually sell their shares and need to calculate capital gains or losses. As an employer, you're responsible for filing Copy A with the IRS and distributing Copy B to employees, all within specific deadlines that vary depending on whether you file on paper or electronically.
Missing these deadlines or filing inaccurate information can result in steep penalties, which is why staying on top of Form 3922 compliance is so important. Between gathering the right details, meeting IRS timelines, and maintaining proper records, ESPP administration can quickly become a lot to manage on your own.
No, Form 3922 is not directly reported on your tax return unless you sell the acquired stock. It's for informational purposes and helps you calculate capital gains or losses when you do sell.
Your employer sends you Copy B of Form 3922 by January 31st of the year following the stock transfer. If you haven't received it, check with your company's HR or payroll department.
It reports the transfer of stock acquired through an Employee Stock Purchase Plan (ESPP) under Section 423(c). It captures details like the purchase price, fair market value, and transfer date, which help calculate tax liability when the stock is sold.
Employees don't file Form 3922; you simply keep it for your records. Employers file Copy A with the IRS (along with Form 1096), either by mail or electronically through the IRS FIRE system, and provide Copy B to employees.